Imagine two people who earn exactly the same salary.
One checks the bank balance calmly, spends with thought, and sleeps peacefully. The other feels a knot in the stomach even on salary day, worries about running out, cannot buy a small thing for themselves, or feels they must rescue everyone around them.
Same income. Completely different experience. Why?
I have thought about this question for years, and my answer is simple. Your relationship with money is not decided by your income alone. It is shaped by what you believe, what you feel, what you saw as a child, and what money has come to mean to you.
Let me ask you a few gentle questions. Please answer honestly, only for yourself.
- Do you feel anxious when you check your bank balance?
- Do you shop when you are stressed, bored or sad?
- Do you feel guilty buying something for yourself?
- Do you find it hard to say no when someone asks for money?
- Do you earn regularly but still feel you never have enough?
If even one of these touched something inside you, please stay with me. Nothing is wrong with you. You may simply be noticing a pattern, and noticing is where every real change begins.
What Does Your Relationship With Money Really Mean?
We usually think of money as numbers in an account. But for most of us, money quietly carries other meanings: safety, freedom, respect, independence, responsibility, or even self-worth.
Your relationship with money has four layers:
- Thoughts: What do you believe about money, wealth, security and success?
- Emotions: What do you feel when you earn, spend, save, give or receive?
- Habits: How do you behave in everyday financial decisions?
- Experiences: What has happened in your life that taught you how to handle money?
I want to be clear about one thing. This is different from learning budgeting or investing. Those skills matter, and I will come back to them. But this article is about the emotional side, the part that decides whether you actually follow what you already know.
7 Hidden Money Patterns That May Be Controlling Your Financial Life
Before we begin, a gentle note. These seven patterns are examples I am using to help you reflect. They are not medical labels or fixed personality types. You may see yourself in more than one, and patterns can change over time.
1. The Avoider: When Looking at Money Feels Uncomfortable
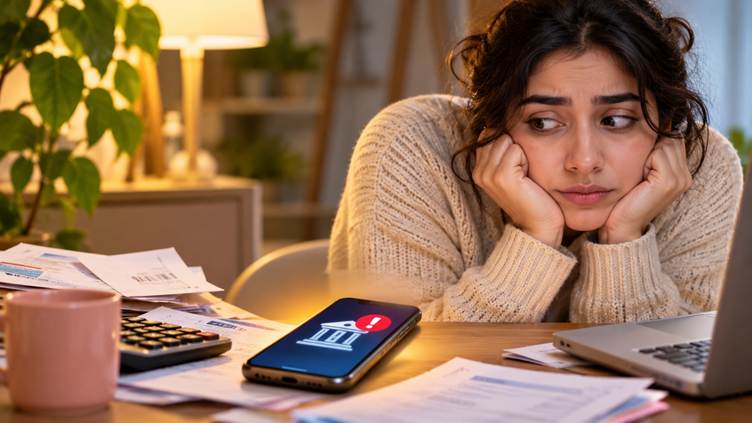
This person delays paying bills, avoids checking the balance, and leaves bank statements unopened. Often the reason is not laziness. It is fear of what they might find, or embarrassment about a past choice.
Think of someone who feels their chest tighten every time a message from the bank arrives, so they simply do not open it. The problem does not disappear. It quietly grows.
Researchers have a name for a similar behaviour in investors, the “ostrich effect”: people look at their finances less when they expect bad news (Karlsson, Loewenstein and Seppi, 2009).
Try this: Set aside ten calm minutes this week to look at your finances, with a cup of tea and no self-criticism. Awareness is always kinder than avoidance.
2. The Emotional Spender: When Shopping Becomes an Escape
A hard day at work, a lonely evening, a small disappointment, and suddenly the phone is full of shopping carts. There is nothing wrong with enjoying a purchase. The question is whether you are buying something you need or buying a feeling.
Research has found that sadness can make people more willing to spend, even when they do not realise it (Cryder, Lerner, Gross and Dahl, 2008).
Try this: Before an unplanned purchase, pause for a minute and ask, “What am I really feeling right now?” Often the answer is not “I need this.”
3. The Over-Giver: When Saying No Feels Selfish
This is the person everyone calls in an emergency. They lend again and again, pay for others, and carry the financial weight of the family, even when their own stability suffers.
Behind this often sits love, but also guilt, duty, or a fear of disappointing someone. Generosity is a beautiful quality. But true generosity should not require you to abandon yourself.
Try this: Practise one respectful boundary, such as “I cannot help with this amount, but I can help with this much.” A boundary is not rejection. It is honesty.
4. The Fearful Saver: When Saving Never Feels Like Enough
Saving is wise. But some people save and save and still cannot relax or use what they have built. Often this comes from a time of insecurity, when money was scarce and the fear of losing it became deeply rooted.
Here is the difference I want you to notice. Healthy saving gives you peace. Fear-driven saving gives you only more fear. Psychologists have also shown that losses feel more painful than equal gains feel good, a idea known as loss aversion (Kahneman and Tversky, 1979). It helps explain why holding on can feel safer than living.
Try this: Decide a fixed amount each month for security and a fixed amount for joy. Both deserve a place in your plan.
5. The Guilt-Driven Spender: When Spending on Yourself Feels Wrong
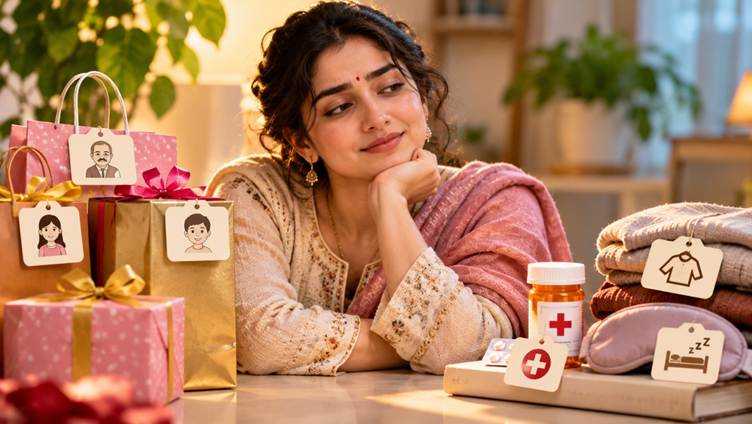
You buy gifts for everyone, fix everyone’s needs, and yet delay your own medicine, your own clothes, your own rest. Many of us, especially women, learned quietly that our needs come last.
That belief may have looked like sacrifice, but over time it can turn into the feeling that we are not worth the spend.
Try this: Write down three reasonable personal needs that you have been postponing. Then choose one and honour it this month.
6. The Approval Seeker: When Money Becomes a Way to Prove Your Worth
A bigger car, a grander celebration, a lifestyle that looks successful, even when it strains the budget. Comparison is a very human habit. Psychologist Leon Festinger described it long ago as our natural tendency to judge ourselves by looking at others (1954), and social media has multiplied it.
Try this: Before a major purchase, ask, “Is this for my needs, or for someone else’s opinion?”
7. The Anxious Earner: When You Work Hard but Never Feel Secure
This person works constantly, fears losing income, and cannot enjoy achievements. Their worth feels tied to their earnings, so rest feels risky.
Here is something important: earning more does not automatically calm every fear about money. If the worry is emotional, a bigger number alone may not settle it.
Try this: Make a small list of progress that is not measured in rupees, such as skills gained, trust earned and problems solved.
Quick view
| Pattern | What it looks like | Gentle question to ask |
| Avoider | Avoids bills and balance | What am I afraid to see? |
| Emotional Spender | Spends to feel better | What am I feeling right now? |
| Over-Giver | Cannot say no | Whose approval am I seeking? |
| Fearful Saver | Saves but cannot enjoy | Is this peace or fear? |
| Guilt-Driven Spender | Puts self last | Do I deserve my own care? |
| Approval Seeker | Spends to impress | Who am I buying this for? |
| Anxious Earner | Works but never feels safe | Is my worth my income? |
Which Money Pattern Do You Recognise in Yourself?
Recognising a behaviour is only the first step. The deeper question is why it happens. If you would like to explore this more gently and in an organised way, I have created a course called Master Your Relationship With Money. It includes a 21-question money-pattern self-assessment that helps you identify your dominant pattern, along with its strengths, blind spots and direction for growth. It is simply there for you if you wish to go deeper.
Where Do Our Money Beliefs Come From?
Nobody is born anxious about money or guilty about spending. These feelings are learned, sometimes without a single word being said.
Childhood and Family Conversations
Think about what you heard growing up:
- “Money does not grow on trees.”
- “We cannot afford that.”
- “Rich people are greedy.”
- “Always save for a difficult day.”
- “Money is very hard to earn.”
Repeated again and again, such sentences quietly become beliefs. Research on family financial socialisation shows that parents and home environments shape how children later think about and handle money (Gudmunson and Danes, 2011). Psychologists Brad Klontz and colleagues have called such deep beliefs “money scripts” (Klontz and Britt, 2011).
Please note, our parents usually said these things out of love and their own experience. The aim is not to blame them. It is to understand ourselves.
Social Conditioning and Comparison
Advertisements, weddings, social media and neighbours all tell us what “success” should look like. Slowly we begin to measure our own financial life against a picture that may not even be real.
Personal Financial Experiences
Not every habit comes from childhood. A job loss, a debt, a sudden medical expense, or an unexpected act of kindness at a hard time can also change how we feel about money at any age. That is why I always say, your story is yours, and it is still being written.
Are You Following Money Rules You Never Questioned?
Many of us carry financial rules for years without asking where they came from. In Master Your Relationship With Money, there are reflective exercises and a belief-rewriting practice that help you explore the influence of family, childhood and society, recognise the beliefs behind your behaviour, question old money rules, and practise healthier responses.
How Emotions Influence Your Financial Decisions
Money decisions are rarely cold and logical. Our emotions walk into every one of them.
- Fear: avoiding decisions, or holding on too tightly.
- Guilt: feeling uncomfortable spending on personal needs.
- Shame: hiding difficulties or avoiding money conversations.
- Stress: impulsive purchases, or postponing responsibilities.
- Comparison: spending to match another person’s lifestyle.
- Pride: protecting an image or proving success.
Here is the simple sequence behind it all:
Trigger → Emotion → Thought → Behaviour → Repeated Pattern
Let me give you an example. An unexpected expense arrives (trigger). You feel fear (emotion). You think, “I am never going to be secure” (thought). So you avoid looking at your accounts, or you make a hasty decision (behaviour). Next time, the same thing happens, and a pattern is born.
The good news is that once you can see this chain, you get a small gap between the trigger and the reaction. In that gap lies your freedom.
A Small Pause Can Change the Way You Respond to Money
The course includes a simple pause practice. You learn to recognise the trigger, notice the emotion, and then choose your response instead of reacting automatically. The aim is never to remove emotions, only to become aware of how they steer you. You can learn this practice in Master Your Relationship With Money. It does not replace financial planning or professional financial advice. It sits beside them.
Money IQ vs Money Mindset: Why You Need Both
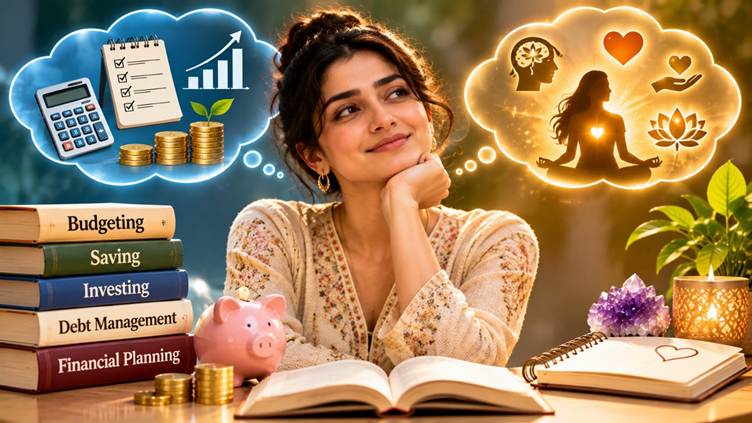
These two are often confused, so let me separate them.
Money IQ is your knowledge: budgeting, saving, managing expenses, understanding debt, investing and planning for the future.
Money Mindset is your inner world: the beliefs, attitudes and emotions that decide how you behave with that knowledge.
Consider these two examples:
- A person knows saving is important, yet spends impulsively whenever stressed.
- Another person knows they can afford something, yet feels guilty buying it for themselves.
7 Practical Ways to Build a Healthier Relationship With Money
1. Observe your habits without judgement.
For one week, simply notice how you spend, save, give and receive. Try: a small notebook, with no scolding allowed.
2. Identify the emotion behind each decision.
Ask whether the choice comes from need, fear, guilt, stress or social pressure. Try: write one word for the feeling before any non-essential purchase.
3. Question old money beliefs.
Ask whether a rule you inherited still suits your life today. Try: complete the line, “I learned that money is…” and then ask, “Is this still true for me?”
4. Create healthy financial boundaries.
You can care for someone and still say no. Try: prepare one kind sentence in advance, such as “I wish I could, but I am not able to this time.”
5. Learn to receive without guilt.
Accept fair payment, a gift or help with a simple “thank you,” without apologising. Try: the next time someone offers, say only “Thank you.”
6. Make conscious choices.
Pause before impulsive purchases and plan for both saving and spending. Try: a 24-hour wait rule for non-essential buying.
7. Separate self-worth from net worth.
You are valuable because of who you are, not because of your salary or possessions. Try: each evening, write one thing you did that has nothing to do with money.
Ready to Understand and Transform Your Relationship With Money?
If something in this article has stirred you, I would love to walk with you further. Master Your Relationship With Money is the course I created for exactly this purpose.
Inside you will find:
- 10 chapters organised across four parts
- A 21-question money-pattern self-assessment
- Reflections and journaling prompts
- A simple pause practice
- A belief-rewriting exercise
- Guidance on childhood and family money beliefs
- Exercises on self-worth, receiving and abundance
- A bonus Money Relationship Workbook
Please remember, this is not a budgeting or investment course, and I make no promise of financial results. It focuses on the emotional and behavioural side of money, and it can sit comfortably beside any financial planning you already do. If you are ready, I welcome you.
Your Relationship With Money Can Change
Here is what I most want you to take from this article. Your money habits are not a label stuck on you forever. They are patterns, and patterns can be understood.
So please be gentle with yourself. Whatever you did with money in the past, you did with the awareness, the fears and the circumstances you had at that time. Today you know a little more.
Remember these five things:
- Awareness comes before change.
- Understanding comes before judgement.
- Conscious choices are better than automatic reactions.
- Financial knowledge and emotional awareness belong together.
- Small, steady steps are enough.
You do not have to judge your money patterns. You have to understand them before you can consciously change them.
Which of these seven money patterns did you recognise in yourself? I would love to read your reflections in the comments.
FAQs
1. What does a healthy relationship with money mean?
It means you can earn, spend, save, give and receive without constant fear, guilt or shame. Your decisions come from awareness and your values, not from automatic emotional reactions.
2. What are the most common unhealthy money patterns?
Common examples include avoiding finances, emotional spending, over-giving, fear-driven saving, guilt about spending on yourself, spending for approval, and anxious overworking. These are illustrative tendencies, not clinical diagnoses.
3. How does childhood influence your relationship with money?
Repeated messages and examples at home can shape beliefs about security, spending and wealth. Research on financial socialisation supports this, though later life experiences also play a role.
4. What is the difference between money mindset and money IQ?
Money IQ is your financial knowledge and skill, such as budgeting and investing. Money mindset is your beliefs and emotions about money. Healthy finances usually need both.
5. How can I change my relationship with money?
Start by observing your habits without judgement, notice the emotions behind decisions, question inherited beliefs, set boundaries, and pause before reacting. Change comes through small, consistent steps.
References
- Cryder, C. E., Lerner, J. S., Gross, J. J., & Dahl, R. E. (2008). Misery is not miserly: Sad and self-focused individuals spend more. Psychological Science, 19(6).
- Festinger, L. (1954). A theory of social comparison processes. Human Relations, 7(2).
- Gudmunson, C. G., & Danes, S. M. (2011). Family financial socialization: Theory and critical review. Journal of Family and Economic Issues, 32.
- Kahneman, D., & Tversky, A. (1979). Prospect theory: An analysis of decision under risk. Econometrica, 47(2).
- Karlsson, N., Loewenstein, G., & Seppi, D. (2009). The ostrich effect: Selective attention to information. Journal of Risk and Uncertainty, 38.
- Klontz, B., & Britt, S. L. (2011). Money behaviors and money scripts. Journal of Financial Therapy, 2(1).
- Lown, J. M. (2011). Development and validation of a financial self-efficacy scale. Journal of Financial Counseling and Planning, 22(2).
- Lusardi, A., & Mitchell, O. S. (2014). The economic importance of financial literacy. Journal of Economic Literature, 52(1).